Toronto Buyers Pay Land Transfer Tax Twice, and Sellers Feel It Later
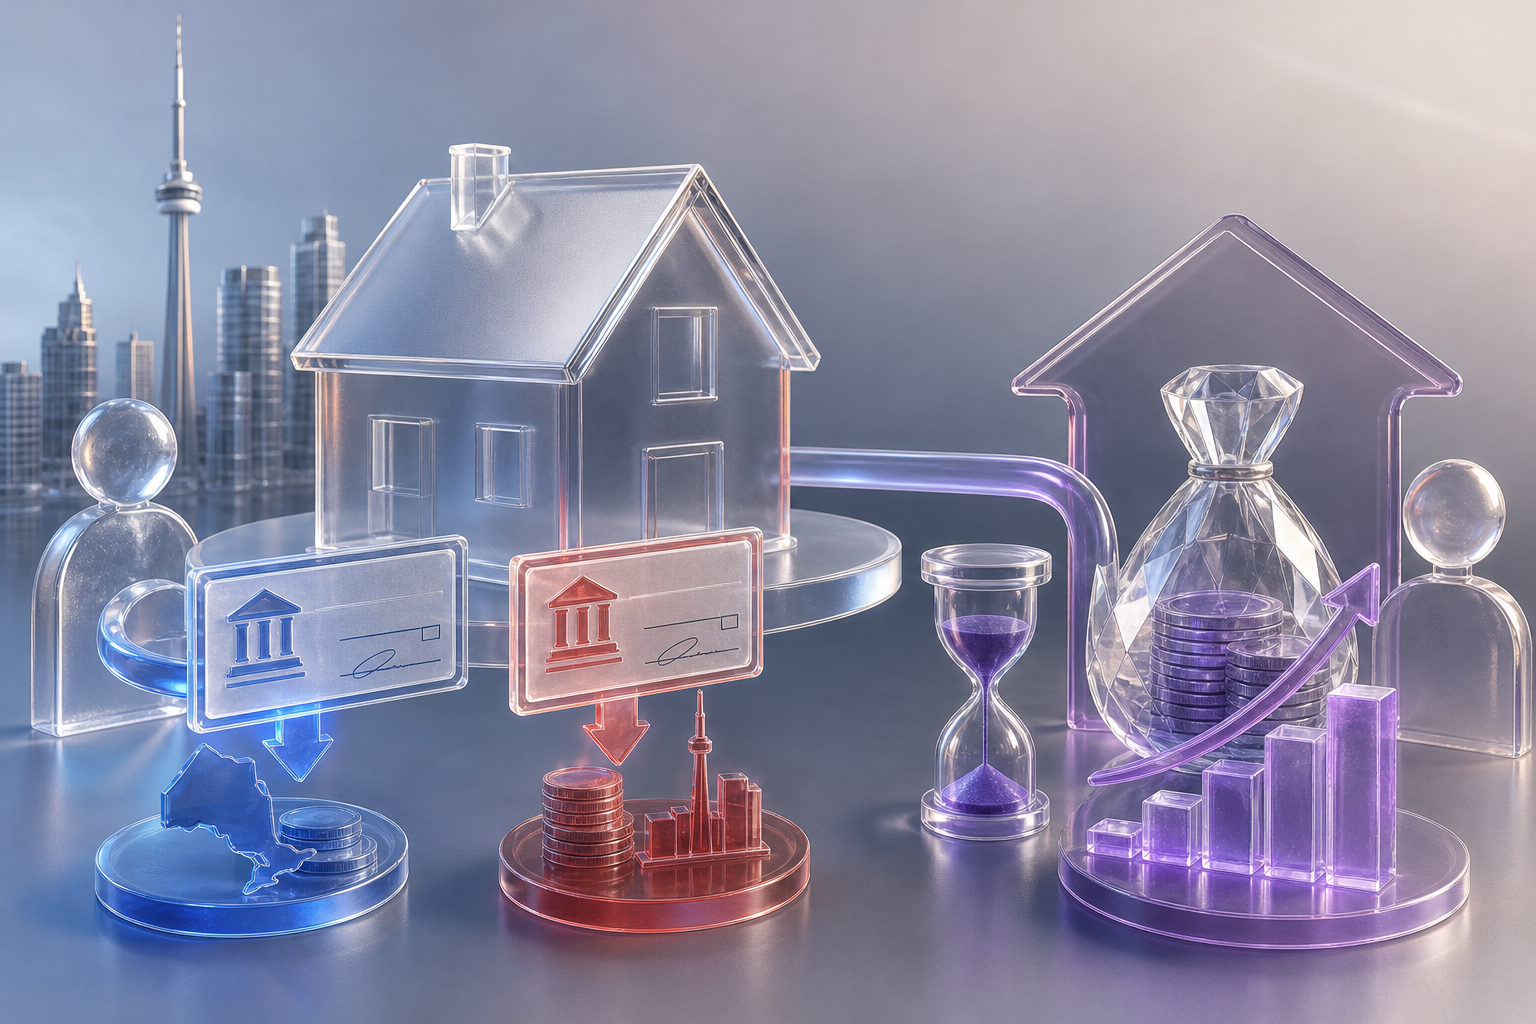
A buyer closing on a Toronto home writes two land transfer tax cheques, one to the province and one to the city, and neither one can go on the mortgage. That cash has to be sitting in the bank on closing day, right beside the down payment.
Most people treat that as a one-time hit for the buyer. Its real reach is wider. A tax charged every time a home changes hands ends up inside the price sellers receive, inside the decision to move or stay, and inside how many homes come up for sale at all. Whether you're buying, selling or setting policy, it helps to see where that money actually comes from.
The tax comes out of the offer
Here in British Columbia, where I work, there's only one layer: the provincial Property Transfer Tax. B.C. municipalities don't charge their own. Even so, the numbers add up fast.
The B.C. rate is 1% on the first $200,000 and 2% on the portion up to $2 million. On a $1,000,000 home with no exemption, that's $2,000 plus $16,000, or $18,000. On a $2,000,000 home it's $38,000. Toronto buyers pay a provincial tax and then a city tax on top of it, so the total for the same price climbs higher.
Now picture a buyer with a fixed amount of savings. Every dollar going to the tax is a dollar that can't go toward the down payment. Say a buyer wants 20% down on a $1,000,000 B.C. home. That's $200,000 plus the $18,000 tax, so $218,000 in cash before legal fees. If they only have $200,000, they either lower their offer or add mortgage insurance by putting less than 20% down.
The useful habit for any buyer: treat the transfer tax as part of the purchase price. It's the largest single cash cost at closing for most people, and planning for it a few months ahead matters even more if your income is self-employed and lumpy.
Sellers pay it quietly
Buyers make offers based on the total cash they have. If the tax takes a bigger slice, the offer shrinks to match. The seller never sees a tax bill, but they see a lower price. Over time, a double layer of tax gets baked into what homes actually sell for.
Sellers also tend to buy again. The family moving up pays the tax on the next home, which is why economists often call it a tax on mobility. Some decide it's cheaper to renovate than to move. Retirees in large houses weigh the tax on a smaller home and stay put. Each of those choices keeps a home off the market that a growing family might have bought.
For sellers, the practical takeaway is to read offers with the buyer's cash-to-close in mind. A buyer stretching for the tax has less room to move on price than the list price suggests.
Relief changes behaviour quickly
The case for these taxes is real. They raise a lot of provincial and city revenue, and supporters argue high transaction costs discourage quick flips. That revenue is exactly why they're hard to remove.
Still, buyers respond fast when transaction costs fall. Ontario saw 8,410 new-home sales in the second quarter of 2026, a rise the Building Industry and Land Development Association tied to the HST rebate program. In B.C., first-time buyers can get a full exemption on homes up to $835,000, and the newly built home exemption reaches properties up to $1.1 million. Those carve-outs work because they lower the cash needed on day one, though anyone just over a ceiling can lose the benefit entirely.
That points to the decision worth holding onto, whatever side of the deal you're on: judge a move by the full cash it takes, including tax, and check every exemption before you set your price. A short conversation with a mortgage broker can map that number out before you start looking, so the tax shapes your plan instead of your closing day.

A buyer closing on a Toronto home writes two land transfer tax cheques, one to the province and one to the city, and neither one can go on the mortgage. That cash has to be sitting in the bank on closing day, right beside the down payment.
Most people treat that as a one-time hit for the buyer. Its real reach is wider. A tax charged every time a home changes hands ends up inside the price sellers receive, inside the decision to move or stay, and inside how many homes come up for sale at all. Whether you're buying, selling or setting policy, it helps to see where that money actually comes from.
The tax comes out of the offer
Here in British Columbia, where I work, there's only one layer: the provincial Property Transfer Tax. B.C. municipalities don't charge their own. Even so, the numbers add up fast.
The B.C. rate is 1% on the first $200,000 and 2% on the portion up to $2 million. On a $1,000,000 home with no exemption, that's $2,000 plus $16,000, or $18,000. On a $2,000,000 home it's $38,000. Toronto buyers pay a provincial tax and then a city tax on top of it, so the total for the same price climbs higher.
Now picture a buyer with a fixed amount of savings. Every dollar going to the tax is a dollar that can't go toward the down payment. Say a buyer wants 20% down on a $1,000,000 B.C. home. That's $200,000 plus the $18,000 tax, so $218,000 in cash before legal fees. If they only have $200,000, they either lower their offer or add mortgage insurance by putting less than 20% down.
The useful habit for any buyer: treat the transfer tax as part of the purchase price. It's the largest single cash cost at closing for most people, and planning for it a few months ahead matters even more if your income is self-employed and lumpy.
Sellers pay it quietly
Buyers make offers based on the total cash they have. If the tax takes a bigger slice, the offer shrinks to match. The seller never sees a tax bill, but they see a lower price. Over time, a double layer of tax gets baked into what homes actually sell for.
Sellers also tend to buy again. The family moving up pays the tax on the next home, which is why economists often call it a tax on mobility. Some decide it's cheaper to renovate than to move. Retirees in large houses weigh the tax on a smaller home and stay put. Each of those choices keeps a home off the market that a growing family might have bought.
For sellers, the practical takeaway is to read offers with the buyer's cash-to-close in mind. A buyer stretching for the tax has less room to move on price than the list price suggests.
Relief changes behaviour quickly
The case for these taxes is real. They raise a lot of provincial and city revenue, and supporters argue high transaction costs discourage quick flips. That revenue is exactly why they're hard to remove.
Still, buyers respond fast when transaction costs fall. Ontario saw 8,410 new-home sales in the second quarter of 2026, a rise the Building Industry and Land Development Association tied to the HST rebate program. In B.C., first-time buyers can get a full exemption on homes up to $835,000, and the newly built home exemption reaches properties up to $1.1 million. Those carve-outs work because they lower the cash needed on day one, though anyone just over a ceiling can lose the benefit entirely.
That points to the decision worth holding onto, whatever side of the deal you're on: judge a move by the full cash it takes, including tax, and check every exemption before you set your price. A short conversation with a mortgage broker can map that number out before you start looking, so the tax shapes your plan instead of your closing day.
Read Next
Morgan Stanley's Record Quarter Shows How IPO Windfalls Become Lasting Wealth Clients
Buy Now or Wait? How July's $6,600 Price Rise Shifts Your Qualifying Math
Brookfield's US$444 Million Bet on Indian Warehouses Shows Where Big Capital Is Heading
6.4% or 6.5%: How a 10-Basis-Point Stress Test Shift Changes Your Approval